Long Reads
In-depth analysis of the major themes moving markets in the UK, the US and around the world. Drawing on extensive datasets, we provide clear, informed commentary on the macroeconomic forces shaping market performance, asset valuations and investor sentiment.
Our analysis reflects our interpretation of the available evidence. It is intended to support your own research and help you make better-informed investment decisions; it should not be regarded as investment advice or a personal recommendation.
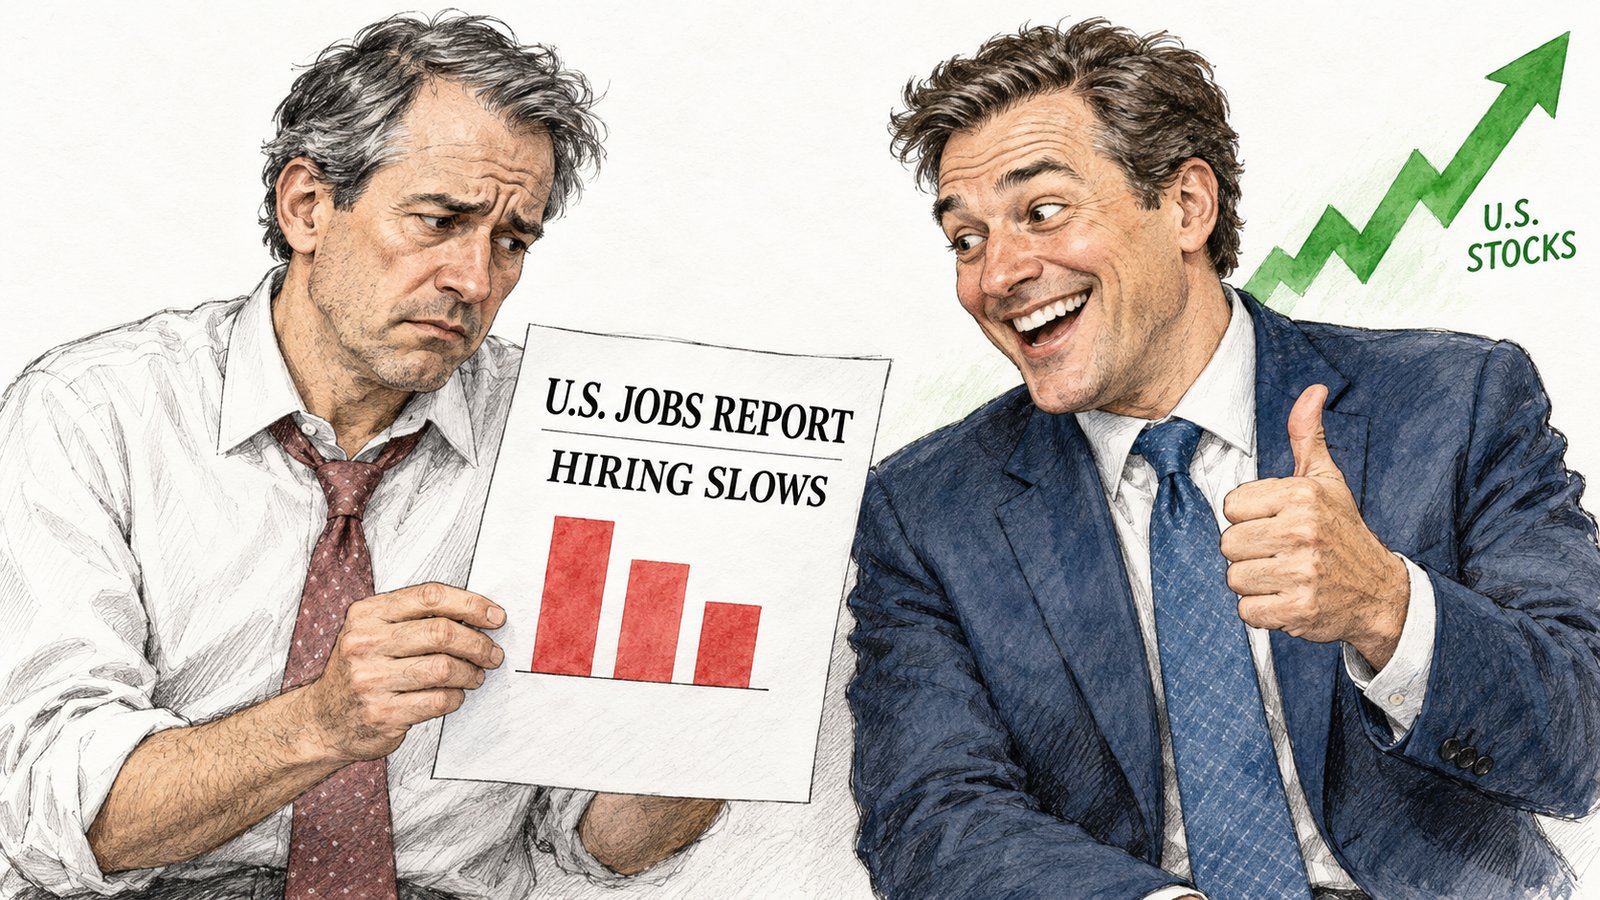
Bad news on US jobs. So why did shares go up?
Why US shares rose after September's weak jobs report, explained in six simple animated steps.
UK Inflation Rose to 2.9%: Why the Underlying Story Is Still Cooling
July's CPI rose to 2.9% on the Ofgem cap increase - while core held at 2.6%, services fell to 3.4% and private-sector pay slowed to 2.8%. What the split means for the Q4 peak, the Bank and the path back to target.
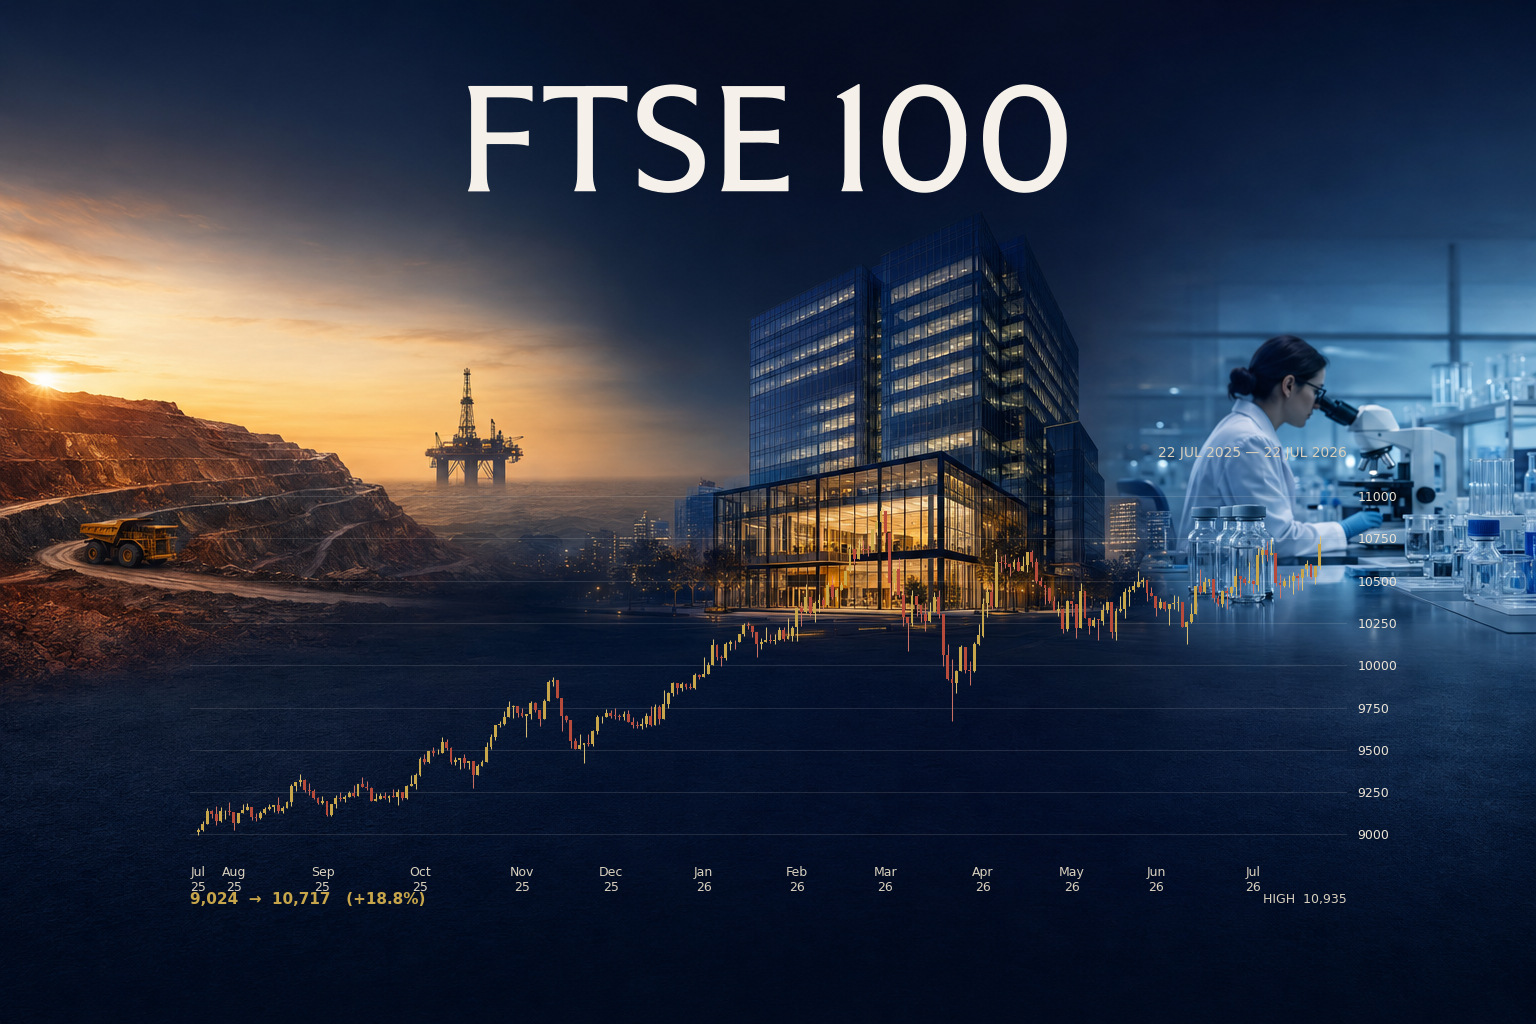
The FTSE 100 After the Re-Rating: What 10,500 Buys You — and What It Doesn't
London's blue-chip index has just delivered its best year since 2009, broken 10,000 for the first time and re-rated in the process. I still think the valuation case holds — but the composition that got the index here is the same composition that could take it back down.
UK Unemployment: The Numbers Behind the Headlines
The headline drop is real, but vacancies are at a four-year low, payrolls are down year on year, and wage growth has cooled. With inflation expected to keep grinding higher into the summer, this looks like a labour market that has stopped worsening — not one that is starting to recover.
UK Inflation Ticks Back Up: What the March Data Really Tells Us
March CPI came in at 3.3%. The obvious explanation is the Middle East. The less obvious story is everything underneath — sticky services, wage pass-through, and a Chancellor with very little fiscal room.