All articles spanning market commentary, company analysis, and macroeconomic research.
GSK is a very large, very stable pharmaceutical business, but sales are creeping up at only 3–4% a year and far too much adjusting is going on in the income statement. I have thrown out the company's 172.0p adjusted earnings and built my own figure of 163.65p per share by adding back only the adjustments I think are permanent. On 6% growth, an 8× multiple and a 5% uplift that gives 2,034.44p against a share price of 1,817.50p — a value opportunity of 11.9%, probability 50%, research grade A. Hold.
Currys' 17-week update is an extremely light one: group like-for-like revenue up 7%, gross margins stable, guidance unchanged. But the business still turns only 1.5p of every pound of sales into profit, and the gross margin has stopped improving. On 13p of EPS, a growth rate of only 2% and an 8.0x multiple I get an actual valuation of 120.64p against a 151.70p share price — a -20.5% value opportunity. Reduce.
Revenue grew 21.7% to $4,812m last year, but the growth rate has fallen every single year since 2021 and the post-tax loss widened to $161m — five losses in six years. Even the adjusted earnings went backwards, from 98.2c to 93.2c. Run on reported EPS of -16.2c the formula gives a valuation of -129.70c against a share price of 21,002c, a value opportunity of -100.6%; even on a make-believe 200c of earnings and 25% growth it only reaches 4,800c, or -77.1%. Pass.
Revenue up 1% in the half, reported operating profit down 14.4%, and costs I expect to rise by about €1.35bn this year against roughly €330m of extra revenue. The balance sheet is in good shape, but I am nervous about the US exposure and a thinner 2027 fuel hedge. On an earnings override of 59.14c, a multiple of 8, growth of 4.5% and a 10% reduction, I get 579.10p against 425.30p — a 36.2% value opportunity. Buy, research grade A, probability 50%, though I am not going to hold them right now.
Buyers remain cautious. Berkeley reiterates April’s around-25% production reduction while maintaining its £1.4bn four-year pre-tax profit plan.
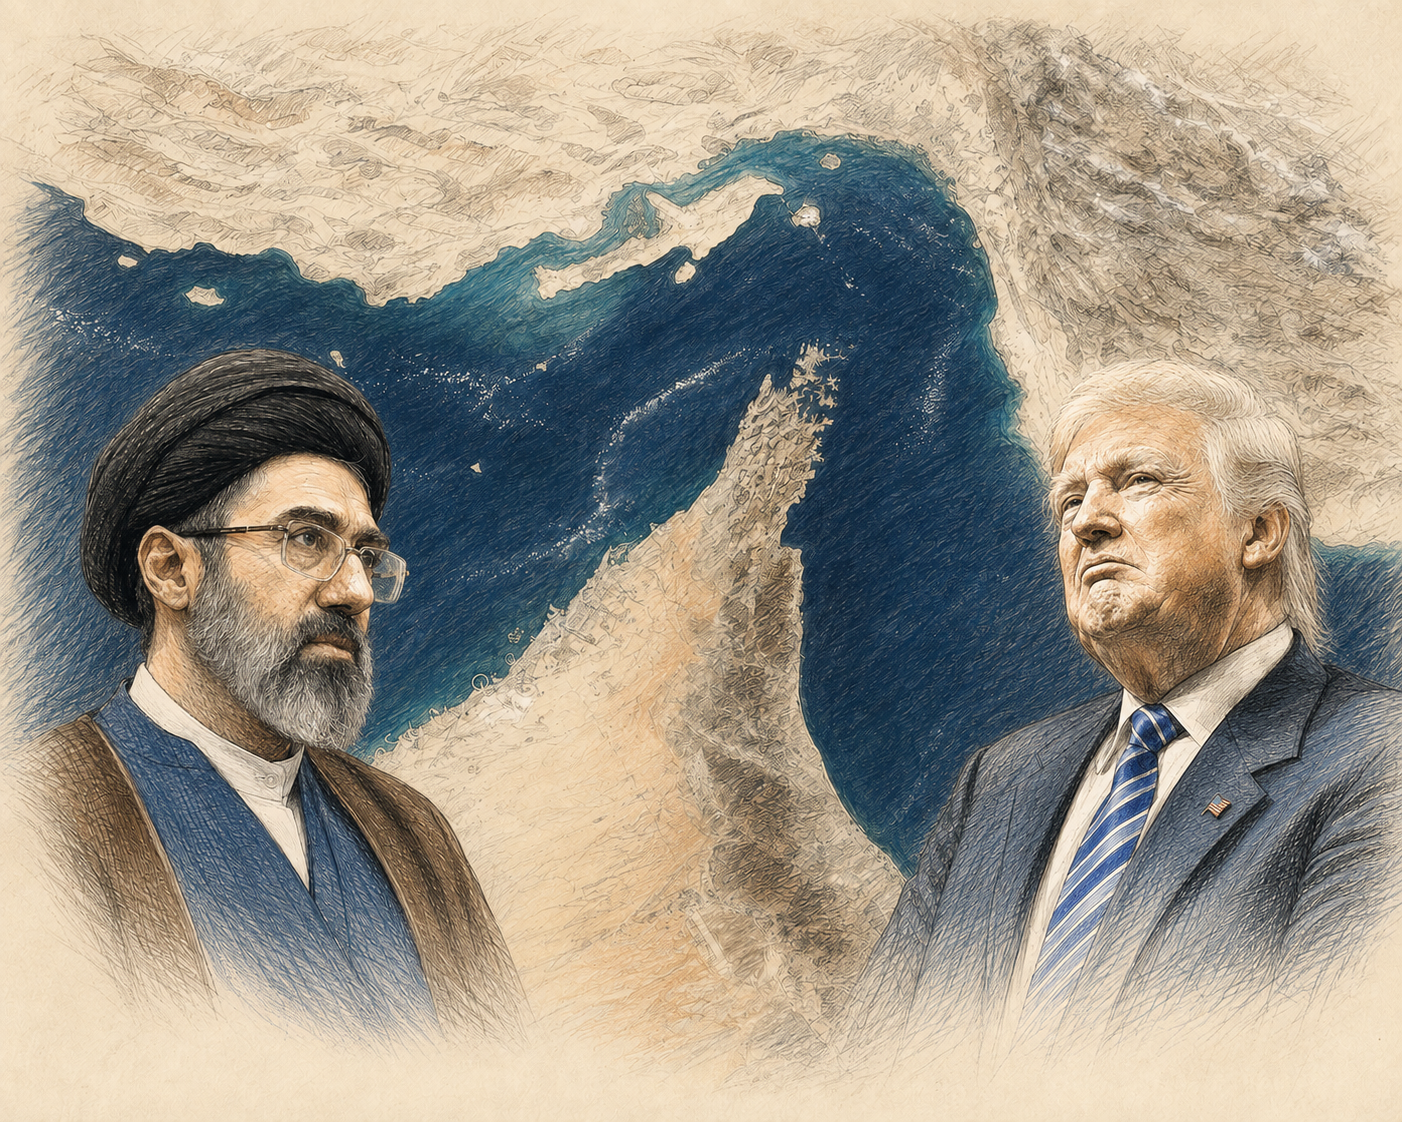
Six months of public ship-tracking at the Strait of Hormuz, 14 March to 3 September 2026. IMF PortWatch, independent directional AIS, Kpler via Reuters and AXSMarine via Signal Group, each charted on its own terms: a collapse, a brief June reopening, and a second squeeze.
Persimmon's first half delivered 13% more completions, 13% more new housing revenue and the joint-best net private sales rate in the sector. But the extra volume came from lower-margin housing association work, the operating margin slipped 30 basis points and net cash swung £288m into a £165m net debt position. On anticipated earnings of 98.2p and 8% growth my base valuation is 1,288.38p, a +12.7% value opportunity against 1,143.50p; my longer three-year valuation, discounted 35%, gives 1,411.49p and +23.4%. Positive, but not enough for investment — Hold.
Keller have had quite a monumental year: revenue up 10.3% to £1.61bn, underlying operating profit up 17.1% at constant currency to £117.9m, margin at 7.3% and net debt down -74.1%. A lot of the growth relates to a single project, I-40, which will slowly wind down — but the order book is a record £1.9bn and I think something else comes in to replace it. On 261.50p of forecast earnings, a 25% growth rate and an 8.00x multiple, that gives 6,276.00p against 3,108.00p — a value opportunity of +101.9%. Buy, grade A+, probability 50%.
JPMorgan is compounding earnings per share at 17.7% a year and the Commercial and Investment Bank is pulling away, with second-quarter 2026 net income of $21.2bn and record revenue in every line of business. The rate tailwind has largely done its work — net interest income excluding Markets is guided broadly flat at around $95bn — but the franchise is very well run and does not get itself into trouble. On 2025 earnings per share of $20.02, a 15% growth rate, a multiple of 9 and a 5% uplift, I get $444.59 a share against $348.40: a value opportunity of +27.6%. Buy, research grade A, probability 50%.
JD Sports has cut profit guidance again, with group like-for-like sales down -3.1% and North America down -6.8%. Three straight years of falling adjusted earnings per share, £1.09bn of pre-tax profit adjusted away in four years, and a yield of only 1.3% while you wait. On 11.70p of earnings, 1% growth, an 8x multiple and an -8% reduction, I get 93.00p against a price of 92.42p — a value opportunity of +0.6%. That is no margin of safety at all: Sell, research grade C, probability 50%.
NatWest seems to really have managed to get their act together. Income up 11% to £8,862m, the margin up 20 basis points to 2.48%, impairments flat at 19 basis points, and the Evelyn Partners deal shifting the income mix towards fees. On a full-year earnings estimate of 84.6p, a 9% growth rate, an 8x multiple and a 5% uplift, that gives an actual valuation of 1,222.30p against 716.00p — a value opportunity of +70.7%. NatWest continues to be a strong buy for me.
Next beat its own second quarter forecast by £70m of full price sales and pushed only £15m of it through to profit — that restraint is exactly why the upgrades keep coming. It is an exceedingly well-run company, but almost all of the positivity is now in the price, and the growth is coming from overseas and Label rather than the core UK brand. On the company's own guided earnings per share of 812.9p, a 6% growth rate and a multiple of 8, I get a valuation of 9,624.74p against 15,045.00p — a value opportunity of −36.0%. Reduce.
ConvaTec keeps growing — four divisions, none of them shrinking, and revenue up 6.6% in 2025. But I'm valuing it on reported earnings of 8.60 cents, not the adjusted 17.6, because the amortisation of acquired intangibles runs through the company every single year. Net borrowing of $1,450m on $2.4bn of sales is too high. On a 6.5% growth rate and an 8x multiple that gives 104.58p against a 229.60p share price — a -54.5% value opportunity. Sell.
Breedon Group FY2025 and H1 2026 share evaluation: revenue has risen every year since 2022, but the growth is bought rather than earned — on a like-for-like basis revenue fell 3% in 2025 and 5% in 2024. Reported earnings per share are down 27% from the 2022 peak, net debt has reached £690.5m, and the payout ratio has run above the company's own target. Value opportunity −62.4%. Proposed action: Avoid.
Greggs' H1 2026: total sales up 7.2% to £1,101.5m, pre-tax profit up 19.7% to £76.0m, and 2,773 shops — but like-for-like growth of just 2.1%, and a valuation of 1,762p against a 1,946p share price. Well run, and fully priced.
Barclays' H1 2026: income up 11% to £16.5bn, pre-tax profit up 16.6% to £6.1bn — 2.1% ahead of consensus — and a return on tangible equity of 14.8%. Strip out the American Airlines gain and the one-off impairment and the half is still good. On 58.95p of override earnings at an 8x multiple I get 750.41p against 530.40p — a value opportunity of +41.5%. Buy, grade A+. The card-arrears drift is the thing to watch.
An interactive atlas of the eighteen companies that supply water to the UK. Map every service area, then shade it by customers, incidents, capital spending or profit after tax — from Thames Water's £585.5m loss to Yorkshire's £270.7m profit.
Severn Trent's FY2026 profit jumped on the new regulatory period, but more than £10bn of debt and acute political risk cap the upside. On my 8x framework the shares screen 19.9% too expensive. A Hold.
Burberry's Q1 update shows green shoots — Americas +12%, Greater China +9% — but on normalised earnings the shares are 44.1% too expensive at 1,082p. A good brand, but a Sell.
British American Tobacco's FY2025 looks like a record year — reported EPS 349.1p — but on normalised earnings the shares screen 15.4% too expensive at 4,382p. A Hold, grade B.
All 50 Crest Nicholson developments mapped — 42 live, 8 in the pipeline. The estate is concentrated in Southern and Eastern England, where a £414k open-market average selling price is most exposed to mortgage affordability.
Revenue down 20.8%, a £35.2m pre-tax loss and a covenant waiver to 31 August — yet Crest Nicholson's discounted net assets are worth 160.97p against a 67p share price.
Broadcom's FY2025 results are monumental — revenue up 23.9% to $63.9bn and reported earnings per share of 477 cents. But at $376.71 the market is extrapolating a volatile, high-thirties growth rate indefinitely. On my framework the shares screen dramatically overvalued: value opportunity −68.1%. Proposed action: Sell.
BP share evaluation: reported profits have been abysmal — largely the self-inflicted cost of unwinding an over-ambitious renewables push — while the underlying business still made around $7.5bn. On a deliberately conservative 37.4p adjusted earnings base with a 10% reduction for the impairment overhang, my valuation is 323.14p against 455.60p — a value opportunity of −29.1%. Verdict: overvalued; I am not paying up for BP here.
Centrica FY2025 share evaluation: a £51m post-tax loss after £1.36bn of profit in 2024, statutory numbers whipsawed by energy prices and derivative re-measurements — but net cash on the balance sheet, a quarter fewer shares, and capital flowing into long-duration infrastructure. After a 24% fall since April, the shares trade almost exactly at my fair value. Proposed action: Hold.
National Grid FY2025 share evaluation: a genuinely improving, defensive, regulated compounder with a real US growth story — margins at 77.4% and profit on turnover of 18.8%. But guidance points to around 7% earnings growth, and I will not chase a 7%-growth utility at this multiple. Value opportunity −34.5%. Proposed action: Sell.
Watches of Switzerland FY26 share evaluation: strong results on US growth, cash generation and balance-sheet repair — but the 53rd week flattered the headlines, margins contracted, and roughly 85% of the statutory profit jump came from exceptionals washing out. At 749.50p the price carries takeover optionality above my 662.52p valuation. Proposed action: Hold.
James Halstead share evaluation: a solid, cash-generative flooring manufacturer with a 6.9% yield, a 49-year record of dividend increases and a strong net-cash balance sheet — but essentially flat sales since 2020, no visible growth catalyst, and a long-term share-price slide. My valuation is 90.02p against a current 127.60p — a value opportunity of −29.5%. Proposed action: Sell.
The NASDAQ keeps climbing, UK airlines bounce back, and I've closed my position. Why the calm doesn't convince me and what the Trump administration's escalation means for short-term opportunities.