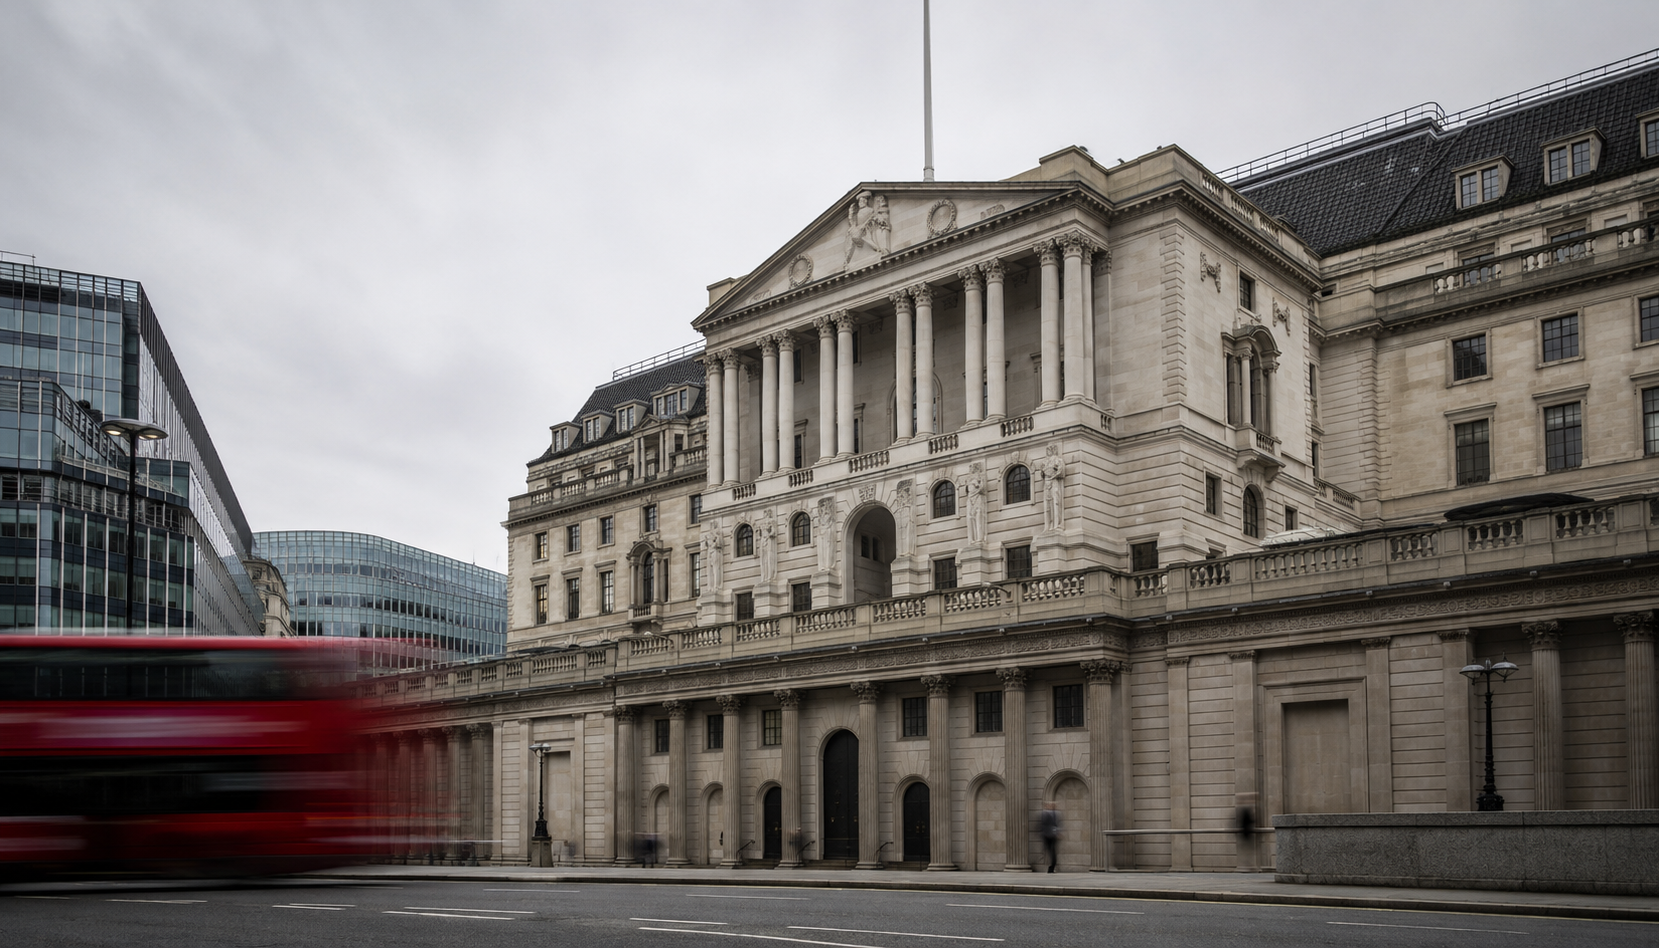
UK inflation and the Bank of England: where next for interest rates?
Equity & Markets
Insight

Newest Articles
Bad news on US jobs. So why did shares go up?
Why US shares rose after September's weak jobs report, explained in six simple animated steps.
UK Inflation Rose to 2.9%: Why the Underlying Story Is Still Cooling
July's CPI rose to 2.9% on the Ofgem cap increase - while core held at 2.6%, services fell to 3.4% and private-sector pay slowed to 2.8%. What the split means for the Q4 peak, the Bank and the path back to target.
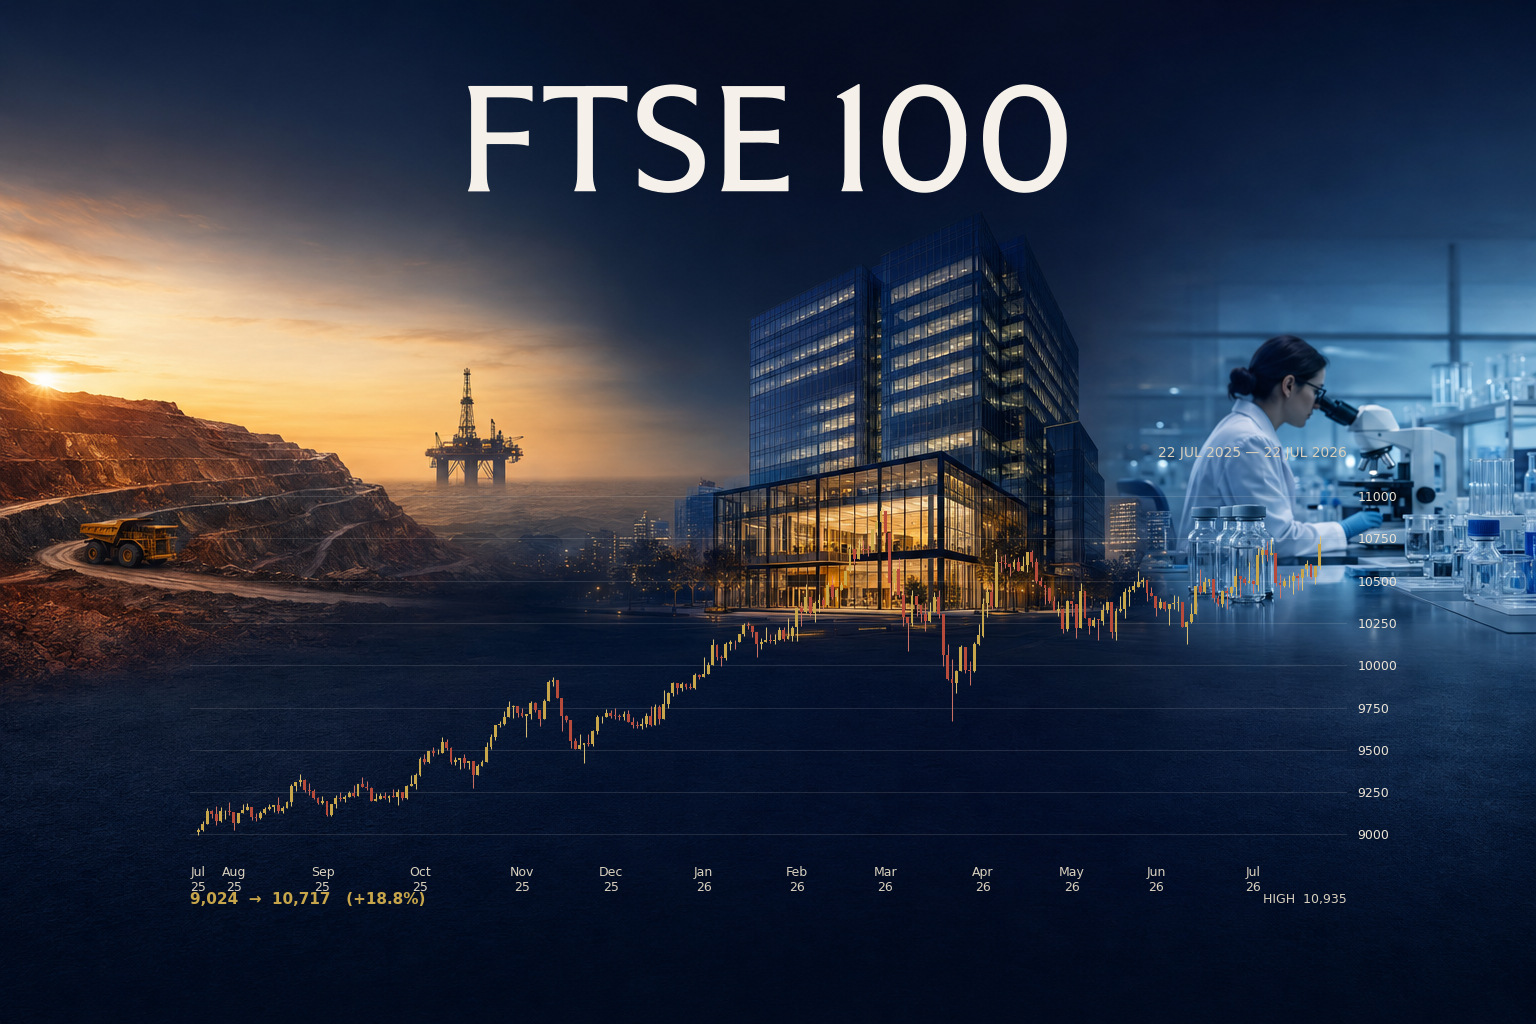
The FTSE 100 After the Re-Rating: What 10,500 Buys You — and What It Doesn't
London's blue-chip index has just delivered its best year since 2009, broken 10,000 for the first time and re-rated in the process. I still think the valuation case holds — but the composition that got the index here is the same composition that could take it back down.
UK Unemployment: The Numbers Behind the Headlines
The headline drop is real, but vacancies are at a four-year low, payrolls are down year on year, and wage growth has cooled. With inflation expected to keep grinding higher into the summer, this looks like a labour market that has stopped worsening — not one that is starting to recover.
UK Inflation Ticks Back Up: What the March Data Really Tells Us
March CPI came in at 3.3%. The obvious explanation is the Middle East. The less obvious story is everything underneath — sticky services, wage pass-through, and a Chancellor with very little fiscal room.
Recent Company Analysis
View all →
Whitbread plc (WTB) — Short: Rooms Up, Profits Down
Whitbread's rooms keep growing and the profit keeps shrinking: revenue up 2.0% to £1.57bn, adjusted profit before tax down -9.1% to £286.8m, and statutory profit before tax down -62.0% after £177.7m of adjusting items. They're struggling with their growth, so I'm applying a 20% reduction to the valuation. On 195.40p of earnings, 1% growth and an 8x multiple I get 1,350.60p against a share price of 2,510p — a -46.2% value opportunity, 60% probability, research grade A. I consider Whitbread to be a short.
Read full analysis →
J D Wetherspoon plc (JDW) — Sell: Full Pubs, Flat Earnings
Wetherspoon sold more and earned less in FY26: revenue up 5.2% to £2,238.0m, but operating profit before separately disclosed items down 17.9% to £120.2m. A well-run business with a property estate worth a good deal more than the balance sheet shows, but with earnings that will not escalate from here. On 59.5p of basic earnings per share, 4.5% growth and an 8x multiple my valuation is 647.36p against 915p — a value opportunity of -29.3%. Sell.
Read full analysis →
Card Factory plc (CARD) — Sell: Standing Still in a Weak Consumer Market
Card Factory's interim results to 31 July 2026: group revenue up 5.3%, but almost all of it is the Funky Pigeon acquisition. UK store like-for-likes fell 2.0%, adjusted profit before tax slipped to £12.7m and net debt rose to £87.4m. On 8.9p of EPS, a 2% growth rate and a 10% valuation reduction I get 63.92p against a 72.70p share price, a -12.1% value opportunity. Sell.
Read full analysis →
International Consolidated Airlines Group SA (IAG) — Buy: A Buy I'm Not Buying Yet
Revenue up 1% in the half, reported operating profit down 14.4%, and costs I expect to rise by about €1.35bn this year against roughly €330m of extra revenue. The balance sheet is in good shape, but I am nervous about the US exposure and a thinner 2027 fuel hedge. On an earnings override of 59.14c, a multiple of 8, growth of 4.5% and a 10% reduction, I get 579.10p against 425.30p — a 36.2% value opportunity. Buy, research grade A, probability 50%, though I am not going to hold them right now.
Read full analysis →
GSK plc (GSK) — Hold: Big, Safe and Barely Growing
GSK is a very large, very stable pharmaceutical business, but sales are creeping up at only 3–4% a year and far too much adjusting is going on in the income statement. I have thrown out the company's 172.0p adjusted earnings and built my own figure of 163.65p per share by adding back only the adjustments I think are permanent. On 6% growth, an 8× multiple and a 5% uplift that gives 2,034.44p against a share price of 1,817.50p — a value opportunity of 11.9%, probability 50%, research grade A. Hold.
Read full analysis →
Currys plc (CURY) — Reduce: Selling More, Keeping Little
Currys' 17-week update is an extremely light one: group like-for-like revenue up 7%, gross margins stable, guidance unchanged. But the business still turns only 1.5p of every pound of sales into profit, and the gross margin has stopped improving. On 13p of EPS, a growth rate of only 2% and an 8.0x multiple I get an actual valuation of 120.64p against a 151.70p share price — a -20.5% value opportunity. Reduce.
Read full analysis →